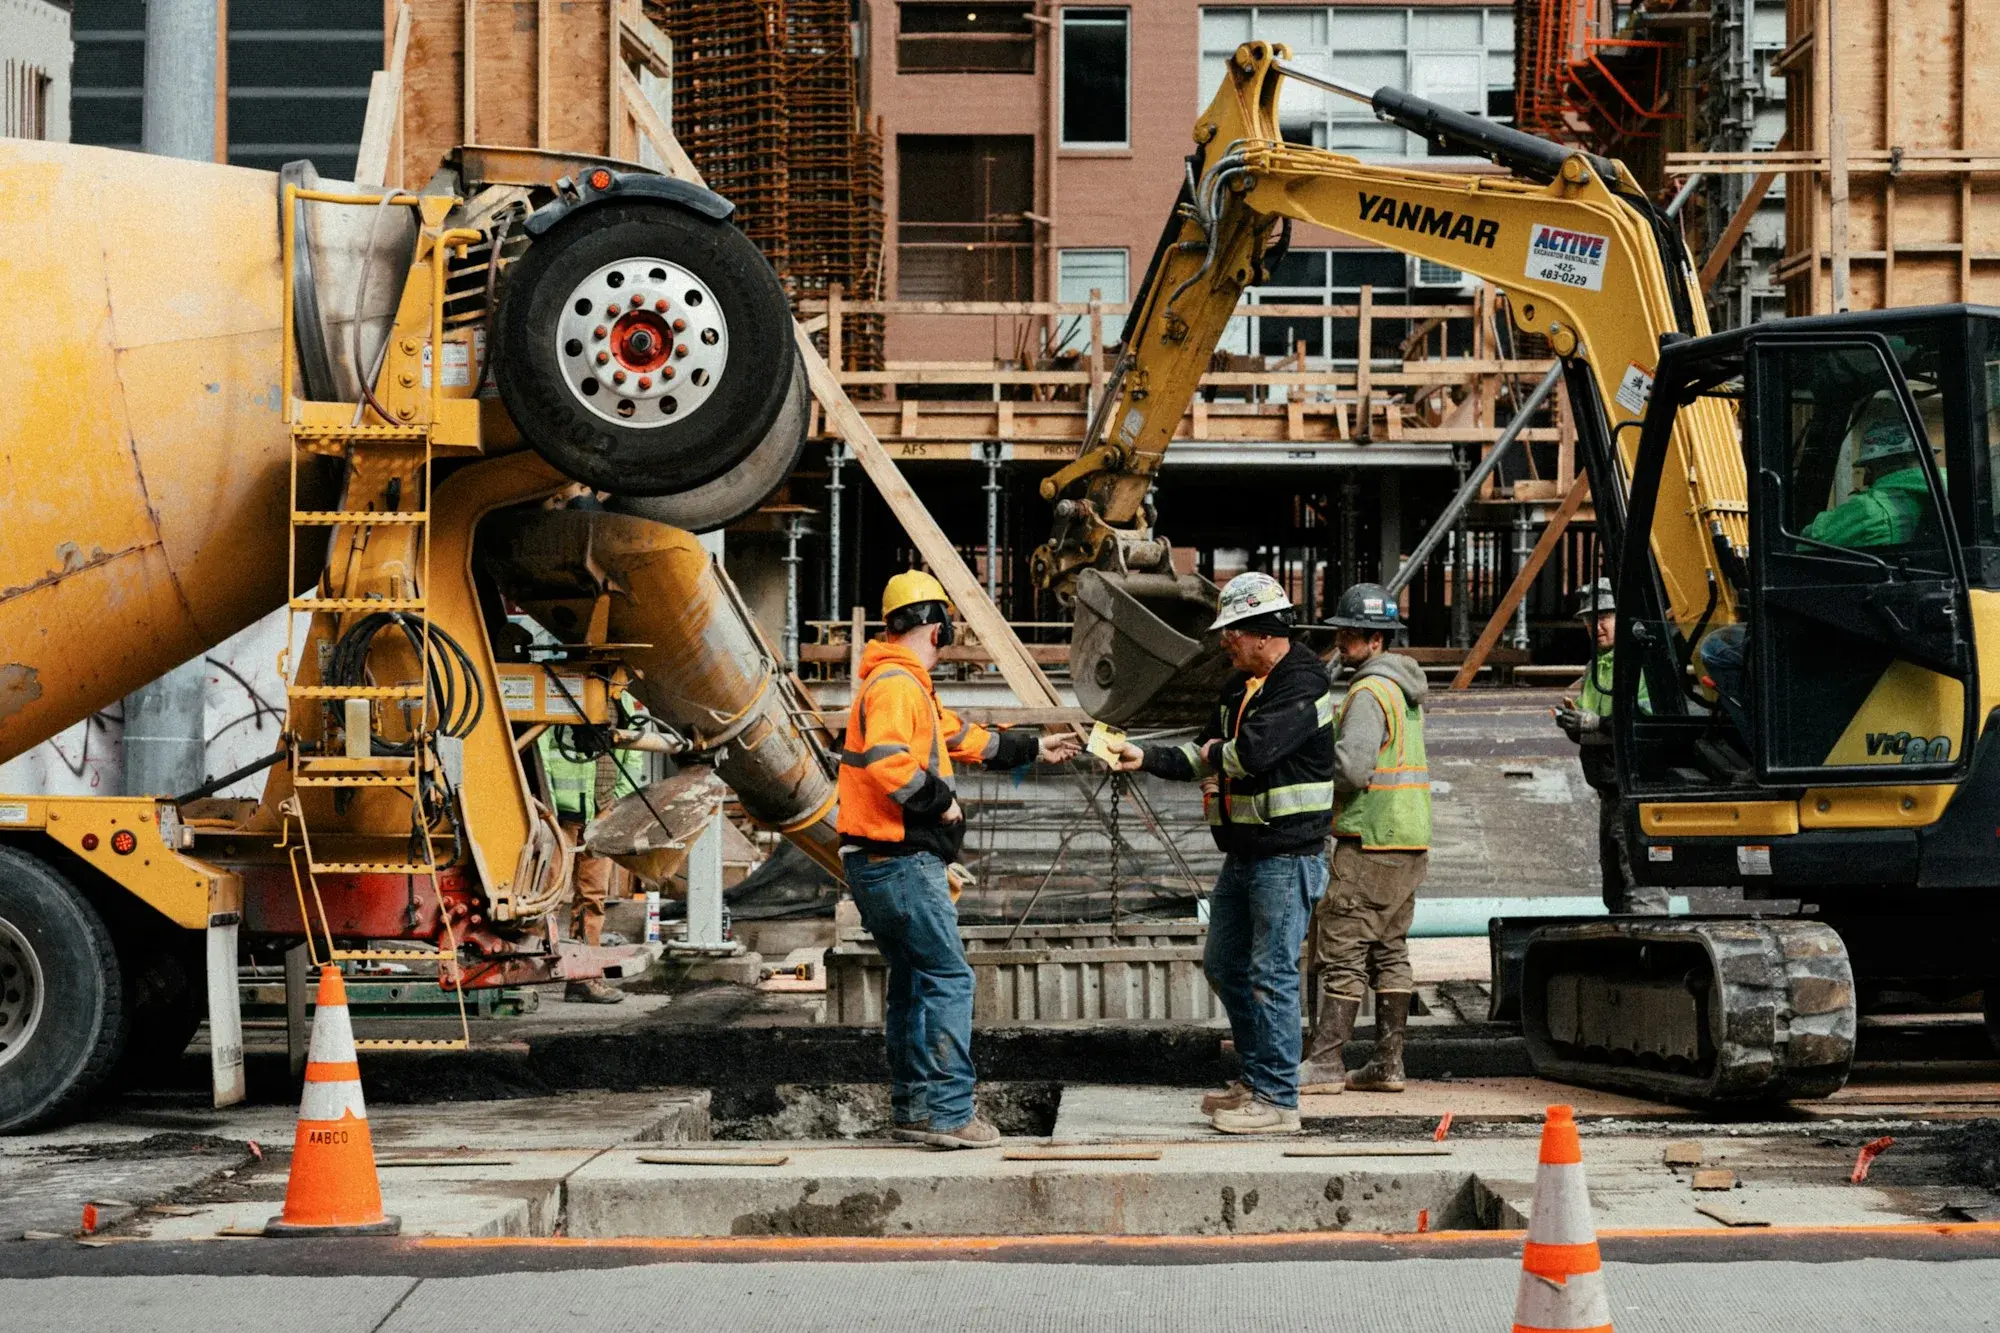
In construction, money goes out long before it comes in. Materials are ordered weeks ahead, subcontractors are booked, plant is hired in and labour is committed to a programme. The client often pays against valuations at set points, sometimes with part of each payment held back until the end. The gap between cost and income is where many building firms lose sleep.
ERP for construction companies is about keeping that gap visible. The aim is to see cost, commitments, income and forecast margin for each job while the work is still moving, not after the final account has been prepared. A system built around jobs, cost codes and cash timing gives site managers, quantity surveyors and directors the same view.
This guide looks at the areas that usually matter most: job costing, materials, subcontractors, plant, valuations and project reporting. It stays at a general level, because contract terms and tax treatment vary between firms. It is written for directors, contracts managers and finance leads in UK building businesses.
Why job costing is harder than it looks for construction companies
On paper, job costing is simple: record what each job costs and compare it with what the job earns. In practice, costs arrive from many sources, at different times, with different levels of detail. Without a consistent structure, two jobs of the same type can look completely different in the figures.
Cost codes that match how jobs are priced
A clear cost code structure is the foundation. Codes should reflect the way the job was tendered and priced, so that actual costs can be compared directly with the estimate. A typical structure separates labour, materials, plant, subcontract work and preliminaries, with codes for each activity or package of work.
- Labour, split by trade or activity
- Materials, split by package or work section
- Plant, both owned and hired in
- Subcontract packages, one code per package
- Preliminaries and site overheads, kept apart from direct costs
Committed cost, not only invoiced cost
A purchase order or subcontract order creates a commitment long before an invoice arrives. Directors need to see committed cost alongside actual cost, because the money has already been spoken for. A job can look profitable on invoices alone while commitments that will be invoiced next month would wipe that out.
Materials from order to site
Materials are one of the largest and most fluid cost areas. Orders are placed against a job, deliveries arrive at a site rather than at the office, and leftovers move between jobs. Each step should be recorded so that the cost lands on the right job at the right time.
Ordering against the job
Every material order should carry the job and cost code it belongs to. Delivery notes should be checked against the order on arrival, with shortages and damage recorded at the gate. A delivery booked to the wrong job is hard to unwind later, so the cost code needs to be right from the start.
Stock on site, transfers and returns
Materials often sit on site for longer than planned. Transfers between jobs, off-cuts and returns to the supplier should all be recorded, because each one changes what a job has really consumed. Without a record, the cost of one job quietly ends up in another. The site log should show the following.
- Delivery notes checked against the order at the gate
- Shortages and damaged items recorded on receipt
- Transfers between jobs logged with the reason
- Surplus materials returned or credited to the correct job
Subcontractors, variations and payments
Subcontractors often carry a large share of a job's cost. Managing them well means agreeing scope, recording changes in writing, checking applications carefully and paying only for work that has been verified. The ERP should make each of those steps visible to the people who need to see them.
Subcontract orders and variations
Every subcontract should have an order that states the agreed scope and value. Variations, meaning changes to the original scope, need their own approval and a clear cost impact on the job. Extra work that starts on site without a recorded variation is a common way margin quietly disappears.
Applications, retention and the Construction Industry Scheme
Subcontractors usually apply for payment against work done, and many contracts hold back part of each payment as retention until later in the project. Where the Construction Industry Scheme applies, contractors must verify subcontractors, make deductions where required and report payments to HMRC each month. The system should keep the evidence for each of these in one place, and the accountant should confirm how the rules apply to your firm. Each subcontractor record should hold the following.
- Subcontract scope, value and approval recorded before work starts
- Each application checked against measured progress
- Retention held and released in line with the contract terms
- Payment records kept ready for the monthly Construction Industry Scheme return
Plant and equipment as a job cost
Plant, such as excavators, cranes, scaffolding and mobile access, is a significant cost in many building firms. Some is owned and carried on the books, some is hired in for a period, and some is shared between jobs. Each type needs a clear rule for how its cost reaches a job.
Owned plant and internal hire rates
Owned plant is often charged to jobs at an internal hire rate. That rate should cover running costs, maintenance and the cost of ownership, and it should be set deliberately by the business rather than guessed each time. Usage logs, whether by hours or days, show which job used which machine. Without that discipline, a machine can look profitable on one job and quietly lose money across the year.
Hired-in plant and off-hire
Hired plant brings its own dates, rates and conditions. The ERP should show when a hire started, which job it sits against and when it went off hire. Plant that stays on a job after the work has finished is a common and avoidable cost. Plant records should track the following.
- Usage recorded by job, with dates and hours or days
- Internal hire rate set and reviewed by the business
- Maintenance and repair costs charged to the machine and the job
- Hire start and off-hire dates tracked against each order
Valuations and the timing of cash
Income on many construction contracts arrives in stages, through valuations or applications for payment. The value certified at each stage depends on the work done, the materials on site, the agreed variations and any retention held back. Matching that income to the cost already incurred shows whether a job is ahead or behind on cash.
What a valuation needs to reflect
A valuation should reflect the value of work completed to a set date, measured against the contract. Materials on site, agreed variations and retention held should all be shown clearly. The ERP helps by keeping quantities, values and dates together, so the valuation is built from the record rather than rebuilt from memory.
Comparing income with cost to date
Two numbers matter most at each valuation: the value certified and the cost incurred. When cost runs well ahead of income, the job needs cash support. When income runs ahead of cost, the firm may be carrying margin before it has been earned. Both situations are easier to manage when they are seen early.
What an ERP for construction companies must report each week
Reporting is where the job costing work pays off. Directors and contracts managers need a view that is current enough to act on, detailed enough to explain variances, and simple enough to review each week. Two reports do most of the heavy lifting.
Work in progress
A work in progress report shows the value of work completed but not yet invoiced, and the value invoiced but not yet earned. It explains where cash is sitting and where income has been recognised ahead of the work. Finance and site teams should look at it together rather than separately. Running it at the same point in every period makes trends easier to compare.
Forecast final cost and margin
The forecast final cost takes the actual cost to date and adds the estimated cost to complete, based on the latest information from site. Comparing that forecast with the original tender shows whether margin is holding. The forecast should be updated regularly, and the reasons for each change should be recorded. Each job's forecast should show the following.
- Cost to date against budget for each cost code
- Committed cost not yet invoiced, shown separately
- Forecast final cost compared with the original tender
- Variations approved, pending and rejected, with values
How to scope an ERP for construction companies
A construction ERP project works best when it starts with the jobs and the money, rather than with every feature a catalogue can offer. Focus on what the business must see each week, then add the detail that supports those views.
Start with job costing and commitments
Job costing, committed cost and the forecast should form the core of the first phase. They answer the questions directors ask most often, and everything else, including purchasing, subcontract administration and reporting, feeds into them.
Decide who enters what, and when
Site managers, quantity surveyors, buyers and accounts staff all touch the same records, but not all at the same time or in the same way. Map who enters materials, who approves subcontract applications, who books plant usage and who signs off valuations. Clear ownership prevents the same cost being entered twice.
Test with a live job
Choose one current job, load its cost codes, budget and open commitments, and run it through a full month. Compare the system's figures with the site's and the accountant's. Any gap is a sign of a rule that needs refining before the rest of the business moves across. The test should include at least one job with variations, one with a subcontract application and one with hired plant, so the awkward cases are covered.
FAQ
What is job costing in construction?
Job costing records each cost against the job it relates to, such as labour, materials, plant and subcontract work, and compares those costs with the budget. It shows whether each job is on track while the work is still in progress. A consistent cost code structure is what makes the comparison reliable.
How does ERP help with subcontractor payments?
It keeps the subcontract scope, approved variations, applications and payment history in one record for each subcontractor. Payments can then be checked against measured progress and retention rules before they are released. Where the Construction Industry Scheme applies, the same records support the monthly returns, though your accountant should confirm the detail.
What is retention in a construction contract?
Retention is an amount held back from payments under many construction contracts, to be released later in the project or after a defects period. The amount and the release conditions come from the contract itself. An ERP should record what has been held and when it becomes due for release.
Can ERP handle valuations for construction work?
A good system keeps the quantities, values, variations, materials on site and retention needed to prepare a valuation. It does not replace the professional judgement that goes into agreeing the value of work done. The benefit is that each valuation is built from a complete and traceable record.
Can plant and equipment costs be tracked per job?
Yes, when usage is recorded against each job by hours or days. Owned plant can be charged at an internal hire rate, and hired plant can be matched to its own dates and conditions. That stops plant costs drifting into the wrong jobs or staying on a job after the work has finished.
What is a work in progress report for a builder?
It shows the value of work completed but not yet invoiced, and the value invoiced but not yet earned, for each job. It helps the business see where cash is tied up and where income has been recognised ahead of the work. Finance and site teams should review it together each period.
Final thought
Construction profit is often decided on site, long before the final account. ERP for construction companies earns its place when it shows job costs, commitments and cash timing while there is still time to act. Good cost codes, disciplined variations and a reliable forecast do more for a job than any end-of-project analysis.
Many firms find that the first phase should focus on job costing and commitments, because those views change decisions every week. Build the structure carefully, test it on a live job, and extend it to purchasing and subcontract administration once the basics are trusted.
Mirex Agency builds ERP systems for small and mid-sized UK firms that need stock, purchasing, finance and operations managed in one clearer system. If your jobs are reported across several spreadsheets, a conversation about your cost codes and approval steps is a sensible place to begin. More on the service is at mirexagency.com/services/erp-solutions.